A car accident can involve several expenses, from vehicle repairs to medical treatment. If you only carry liability insurance, some of those costs may be covered by your policy, while others could become your responsibility.
Liability-only car insurance is designed to help pay for injuries and property damage you cause to others in a covered accident. Understanding how these payments work can help you see what protection you’re purchasing, how coverage limits apply, and where you may face additional expenses.
One Accident, Several Expenses: What Does Liability Insurance Cover?
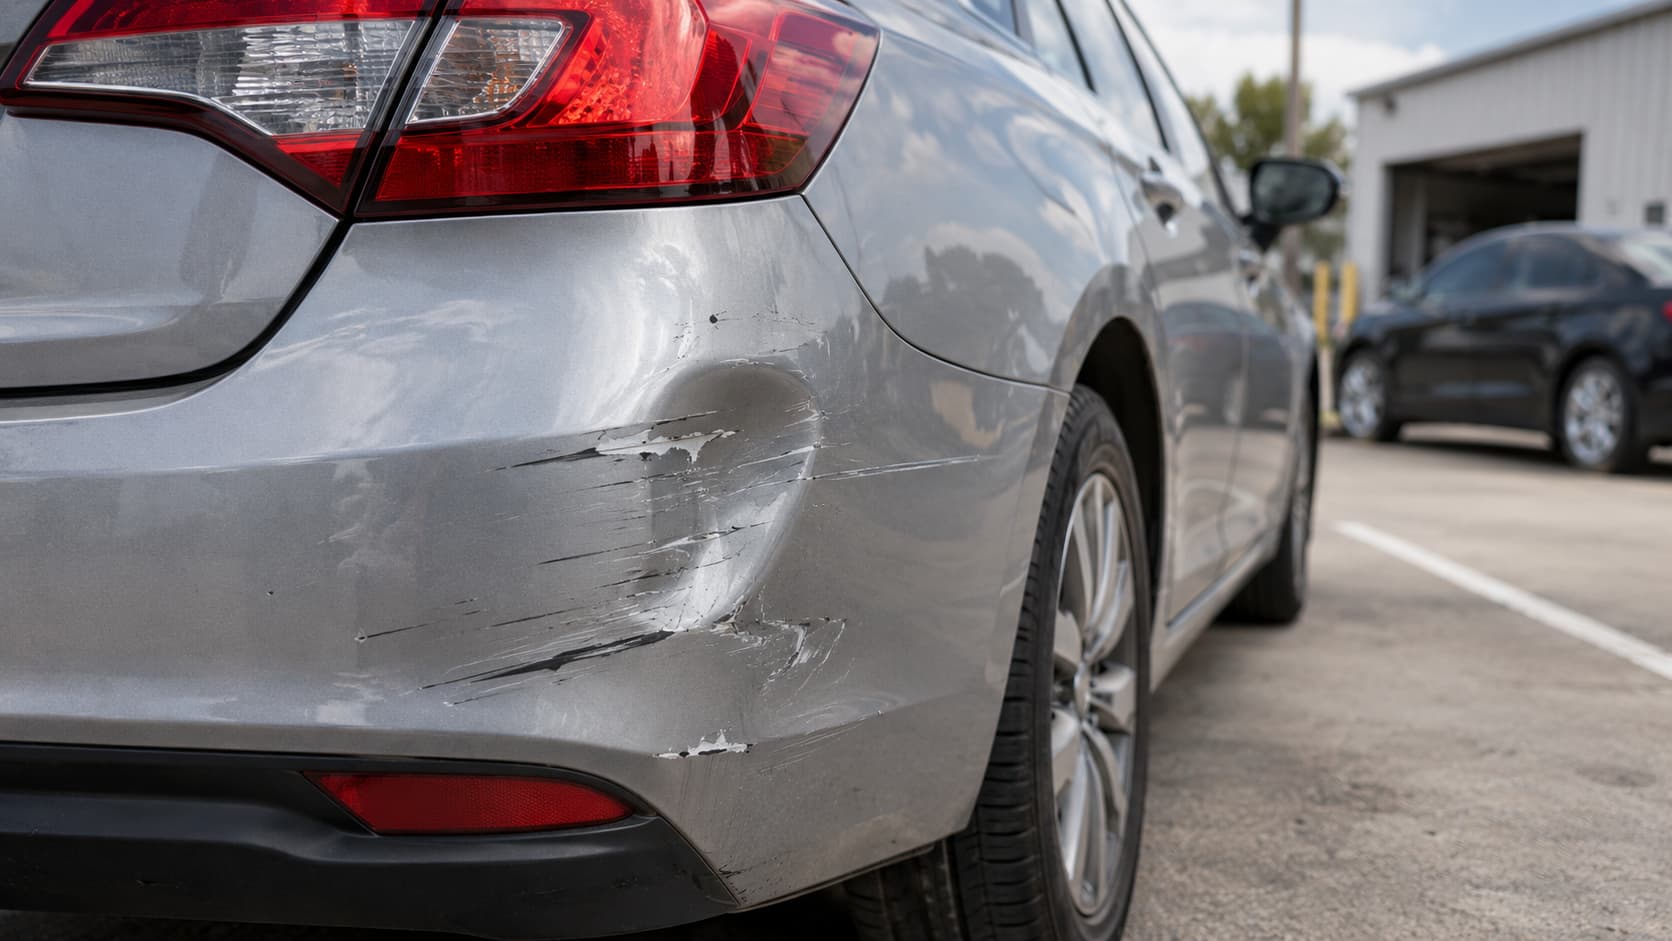
Consider a driver in Broken Arrow who accidentally runs into another vehicle at an intersection. Both cars are damaged, and the other driver receives medical treatment for an injury.
Although everything happened during the same accident, liability insurance treats the expenses differently.
| Accident Expense | How Liability Insurance May Apply |
| Repairs to the other driver’s vehicle | Property damage liability may cover eligible repair costs |
| Medical treatment for the injured driver | Bodily injury liability may cover eligible medical expenses |
| Lost wages resulting from the other driver’s injury | Bodily injury liability may cover eligible lost income |
| Repairs to your own vehicle | Not covered by your liability insurance |
Bodily injury liability applies to covered injuries you cause to others. In addition to medical treatment and lost wages, it may cover other injury-related damages, including pain and suffering.
Property damage liability applies to damage you cause to someone else’s property. This can include another vehicle, a fence, a mailbox, or a building.
These two types of auto liability coverage address different accident-related expenses, and each has its own payment limits. The amount paid depends on the circumstances of the accident and the terms of the policy.
What Determines Whether Liability Insurance Will Pay?
Being involved in an accident doesn’t automatically mean your liability insurance will pay every claim.
The insurance company must determine who was responsible, whether the accident is covered, and which expenses qualify for payment.
Returning to the Broken Arrow intersection accident, the insurer may review driver statements, photographs, accident reports, and other available evidence to determine what happened.
If the insured driver is responsible, the company evaluates the damage and injuries claimed by the other driver. Eligible expenses may then be paid according to the policy’s coverage limits.
Other factors can also affect the outcome, including:
- Driver eligibility: Whether the person operating the vehicle was covered under the policy.
- Policy status: Whether insurance was active when the accident occurred.
- Policy exclusions: Whether any restrictions apply to the driver, vehicle, or circumstances of the accident.
Liability insurance may also provide legal defense if the insured driver faces a lawsuit involving a covered accident, subject to the policy’s terms.
What Happens When the Damage Costs More Than Your Coverage?
Even when an accident qualifies for liability coverage, the insurance company can only pay up to the applicable policy limits.
Oklahoma requires drivers to carry minimum liability insurance limits of 25/50/25:
- $25,000 for bodily injury to one person
- $50,000 for bodily injury per accident
- $25,000 for property damage per accident
These limits apply separately to injuries and property damage.
Returning to the intersection accident, suppose the other vehicle requires $30,000 in repairs.
If you carry Oklahoma’s minimum $25,000 property damage liability limit, your insurer may pay up to $25,000 toward the covered damage.
| Property Damage Expense | Amount |
| Eligible damage to the other vehicle | $30,000 |
| Maximum available property damage coverage | $25,000 |
| Amount potentially remaining | $5,000 |
The remaining $5,000 could become your personal financial responsibility, depending on the circumstances of the claim.
If the other driver also has injuries, those eligible expenses are evaluated under the separate bodily injury liability limits. The bodily injury coverage cannot be used to increase the property damage limit.
This is why an accident can create expenses beyond what a liability-only policy is able to pay.
Which Accident Expenses Would You Still Have to Pay Yourself?
Liability-only insurance primarily provides protection against covered claims involving other people. It generally does not pay for damage to your own vehicle.
In the intersection accident, your property damage liability may help repair the other driver’s car. However, if your vehicle also needs repairs, you would typically need to pay for them yourself unless you have applicable collision coverage or another source of recovery.
Other expenses generally not covered by liability-only insurance include:
- Weather-related damage: Hail, flooding, and certain storm-related losses involving your vehicle.
- Theft or vandalism: Damage or loss caused by theft and other non-collision events.
- Your own injuries: Medical treatment for injuries you sustain in an accident.
Comprehensive insurance generally covers certain non-collision losses, including hail and theft, while collision insurance can help pay for damage to your vehicle from covered accidents.
Separate coverage, such as medical payments insurance, may help with eligible injury expenses.
Liability-only insurance also doesn’t guarantee payment for every accident involving another person. Exclusions, coverage conditions, and the determination of responsibility can affect which expenses are covered.
What Broken Arrow Drivers Should Understand Before Choosing Liability-Only Insurance
Liability-only car insurance can provide financial protection when you’re responsible for a covered accident involving injuries or damage to someone else. However, the coverage has limits, and certain expenses may remain your responsibility.
Understanding what your policy pays for is especially important when considering how an accident could affect your finances, including repairs to your own vehicle or damages that exceed your insurance limits.
Broken Arrow drivers considering liability car insurance can review Oklahoma’s minimum coverage requirements and available insurance options before requesting a quote.
Get started with a Broken Arrow liability insurance quote today.